

Good Morning,
There are small signs beginning to appear that BigTech won’t be the same after the AI boom.
Just a little note on Alphabet’s bifurcating Earnings. Google just released maybe the most disappointing Earnings in its history. I don’t say that lightly. While its Search business declines, it’s investing into TPUs and Google Cloud successfully, finally diversifying its business model to be a bit more sustainable as a Hyperscaler incumbent.
The transition is so bumpy, you’d be hard pressed not to question the plan.
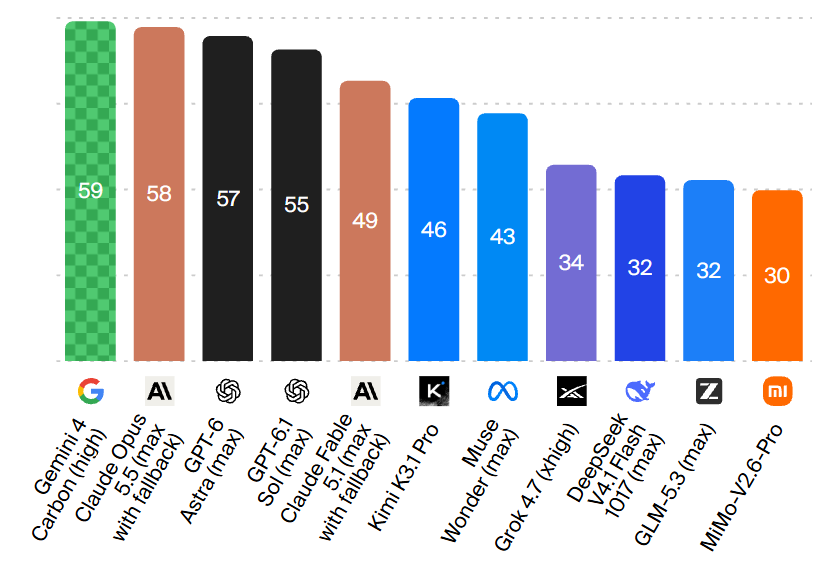
Google release Gemini 4 Carbon, their strongest model with state-of-the-art cybersecurity and long horizon capabilities.
Alphabet reported negative free cash flow (FCF) of $9.07 billion during the third quarter.
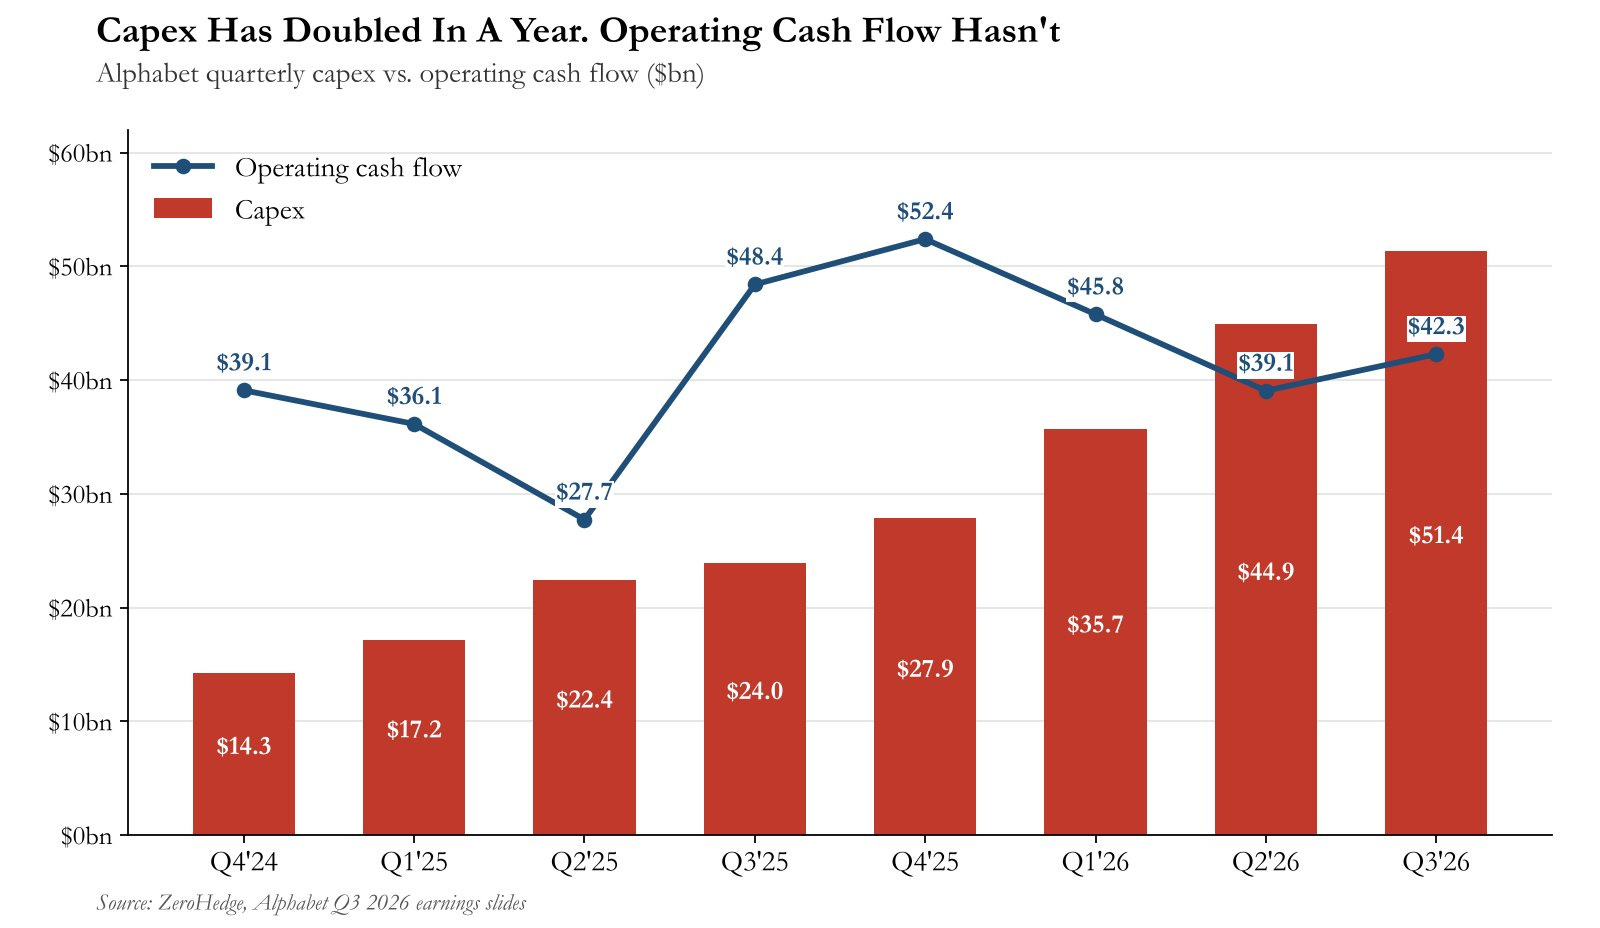
Google’s Capex rose 114% y/y to $51.4bn (below est $55.8bn). But operating cash flow fell 13% y/y to $42.3bn, far short of the $53.9bn consensus.
Hyperscalers are Entering Awkward Years Ahead
Capex is eating into Operating cash flow.
Alphabet’s TPU and Cloud Business is Upon Us
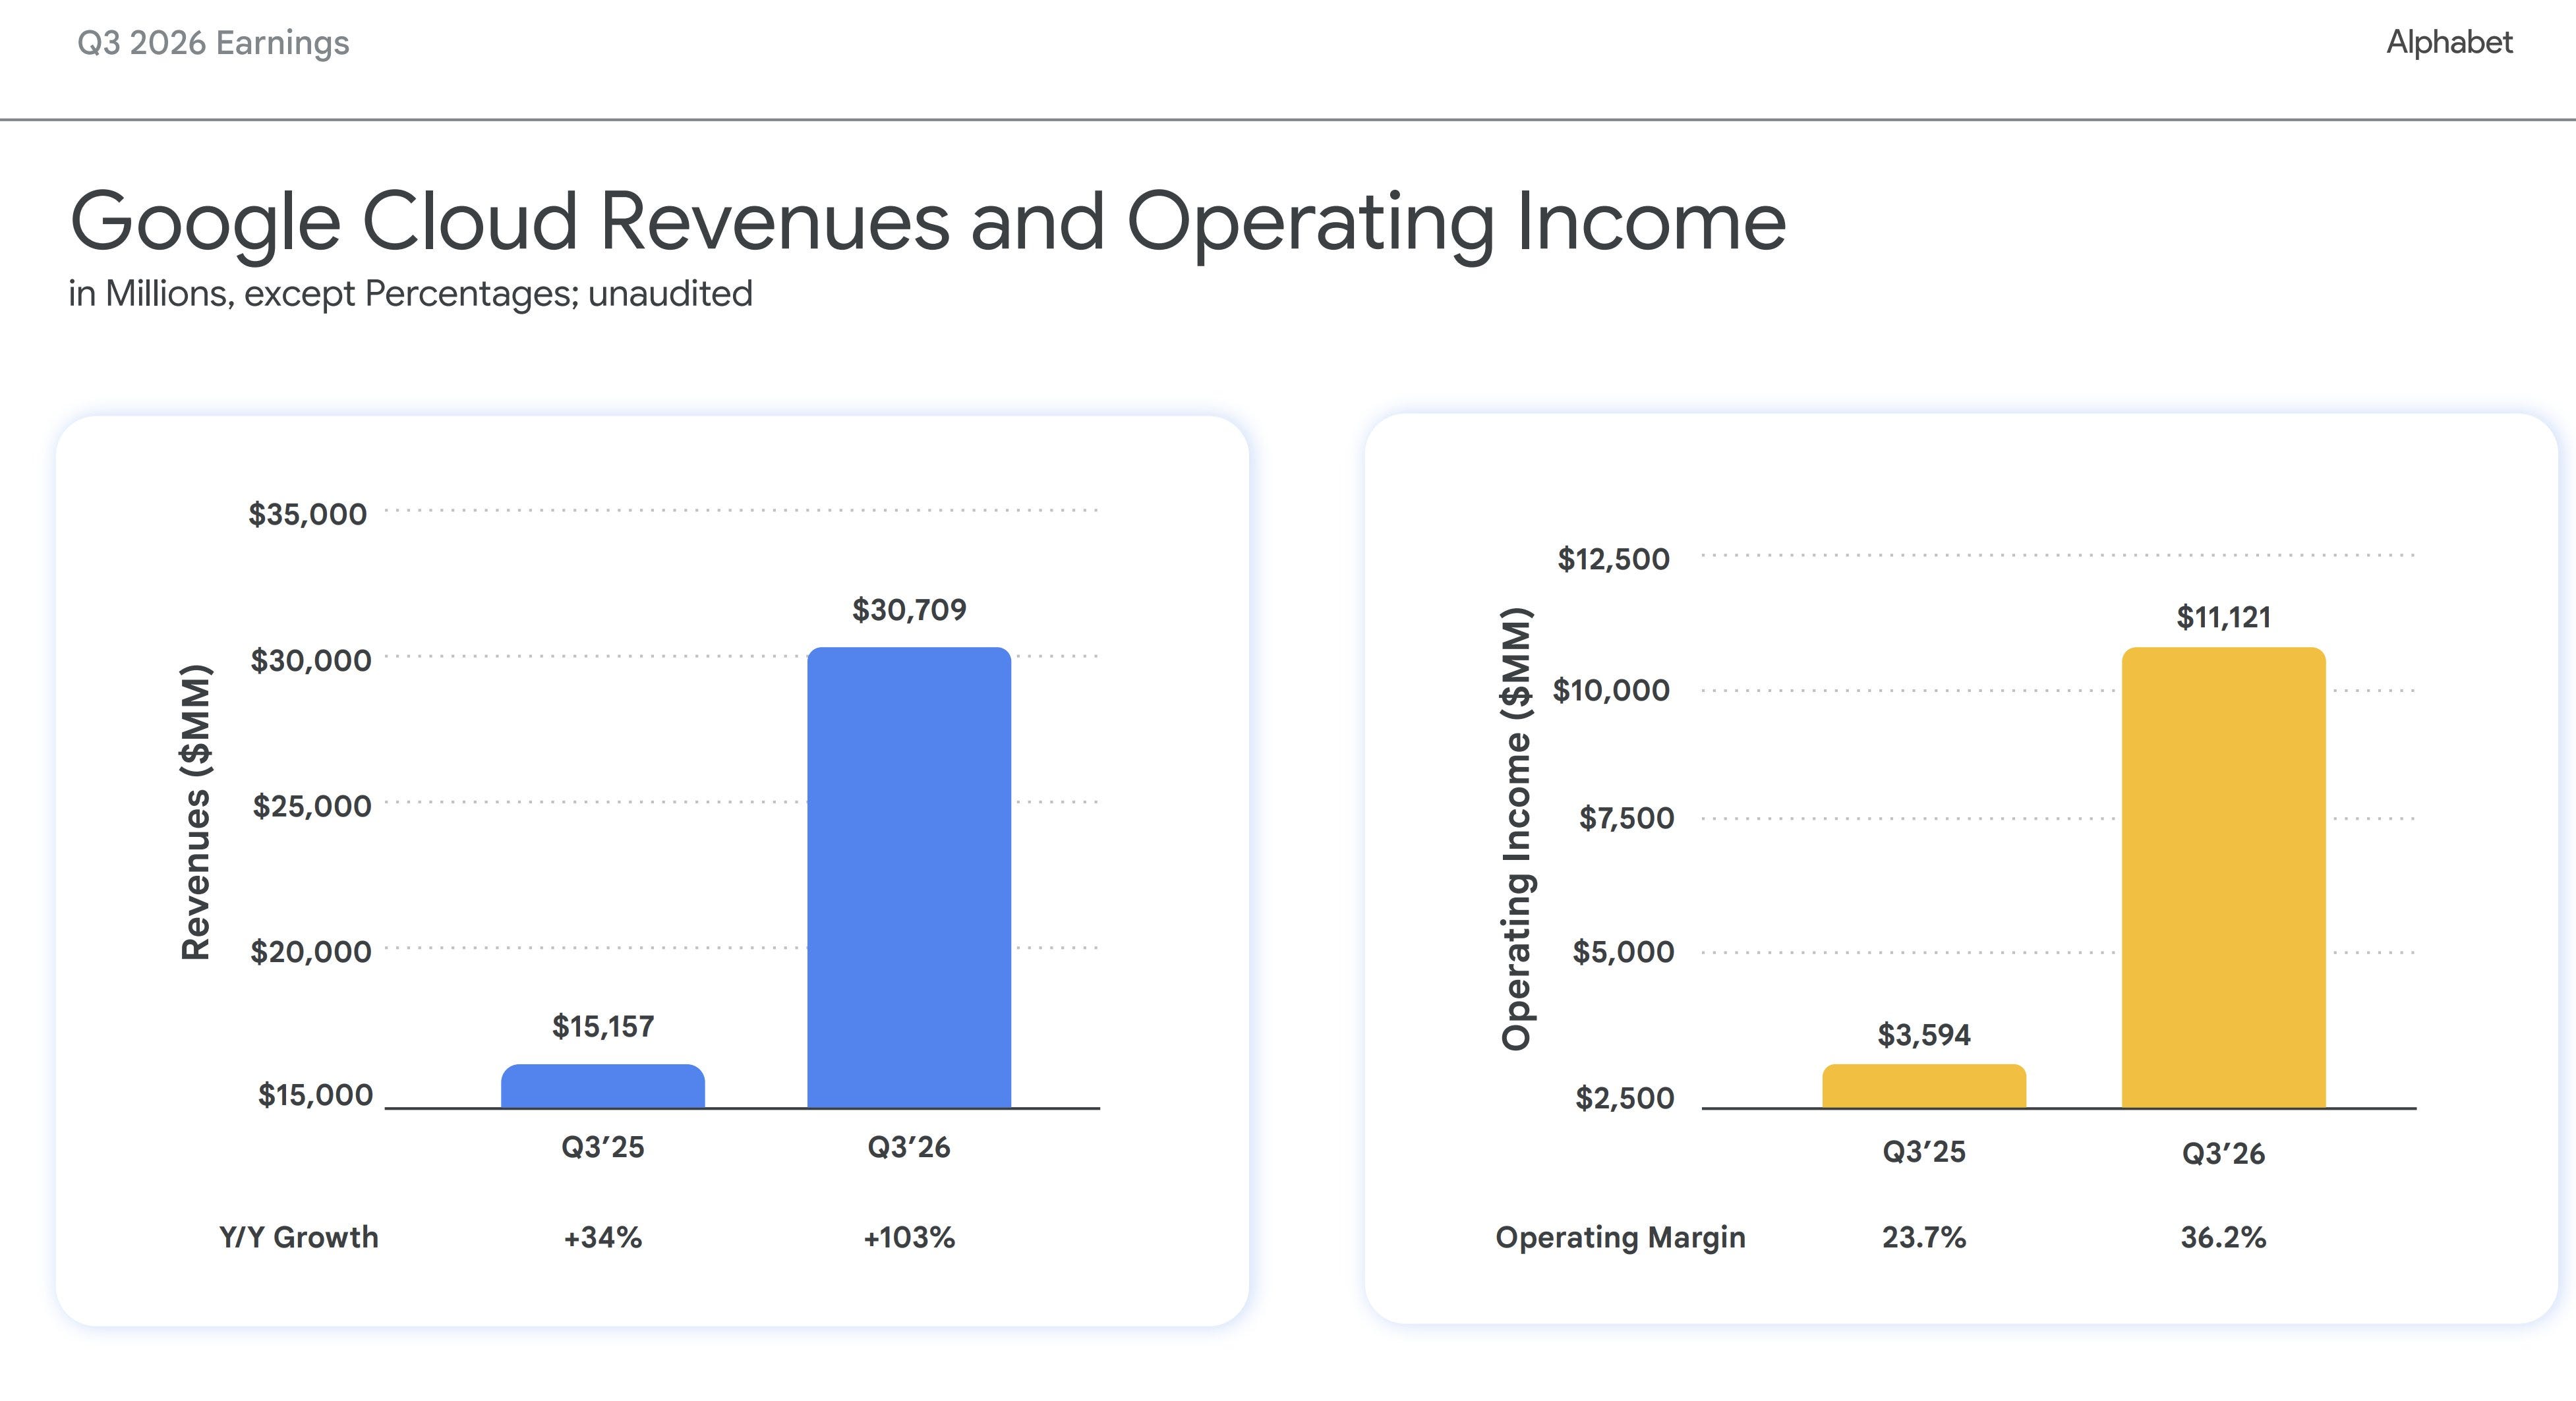
Google Cloud revenue doubled year-over-year, reaching $30.7 billion (up 103% YoY from Q3 2025).
Cloud operating income tripled to $11.1 billion, expanding the unit's operating margin to 36.2%.
Alphabet reported free cash flow of (negative) -$9.07 billion in Q3 2026.
Long-term debt is up +479% in a year, to $125.1B. Not counting debt off the books obviously.
Incumbents won’t survive the way we remembered them, the shift is already occurring.
‘Don’t be Evil’ in Overspending
Is Capex Even Sustainable?
There are serious concerns for Hyperscalers and their Capex to negative FCF. Capital expenditure ballooned to $51.4 billion in Q3 (+114% YoY), primarily allocated to data center expansions, server hardware, and TPU inventory buildouts. Google’s AI chips (TPUs) are going to be a great business, likely the number #2 ahead of AMD chasing Nvidia by the end of the decade.
Google’s Cash burn is not great: Massive CapEx outlays, paired with a $5.2B European Commission regulatory fine payment, resulted in a negative free cash flow of -$9.1 billion for the quarter.
Google’s FCF was essentially $7 Billion less than analysts expected. The stock will have a likely hard end to the week. GOOG 0.00%↑. (Down 9% after hours on Oct 28).
Google Search and YouTube growth is anemic, certainly not what we’ve expected from BigTech over the last few decades. They are essentially being beaten in AI by both Anthropic and OpenAI. Where are the bright spots?
Google Claims Carbon is better than Opus 5.5.
But for how many days, weeks and can they replicate it in a good cadence?
Too Big to Fail but a $4 Trillion Company?
Google’s revenue is still $127.6 Billion and grew 25%, but there are structural issues now at the company. Spending big for an uncertain future: Alphabet maintained its full-year capex forecast after lifting guidance to between $195 billion and $205 billion during Q2.
TPU sales are included in Google’s Cloud Revenue, so they can pretend to be something they are not.
Post Q3 Earnings, the future of Google is now open for debate.
The Future of Search is Murky
So many dualities in Alphabet’s Earnings. So while outbound search clicks from Google to external websites are in a state of measurable (and incredible) decline, this even as total Google search query volume remains high or continues to grow. How do you monetize zero click journeys well? It’s the beginning of the end of an era.
