Good Morning,
I have been absorbing the stunning Midterm “blue wave” elections results and what it means for datacenter moratoriums and a BigTech backlash. While Anthropic this week revealed its amended or revised S-1/A with its particularly weird warnings around about being near to RSI is its best attempt at a marketing pitch or an IPO stunt. Anthropic, an AI startup whose ties to Amazon and Alphabet are so solid you could consider circular financing itself to be its real moat and competitive advantage that is ANT’s distinct and unusual position of privilege.
What is Anthropic’s Moat Anyways?
The concentration of premium token spend of the top Enterprise AI customers is certainly also about a result of having consistently the top frontier models, that is perhaps the result of having recruited the highest paid AI researcher and being able to retain them1. All this is quite stunning for a company that’s just five years old. Recently Menlo (who is an early investor in Anthropic), release their latest State of Enterprise AI report.
Anthropic (not Palantir) has been the key beneficiary of Enterprise AI concentration being the moat of the Generative AI movement. While AI adoption is not as great as some AI optimists would have you believe, Enterprise AI is scaling in the 2020s. Anthropic is at the frontier of that ramp and it certainly looks like a winner-takes-all leadership. We found out in 2026 that Google or OpenAI are struggling to keep up.
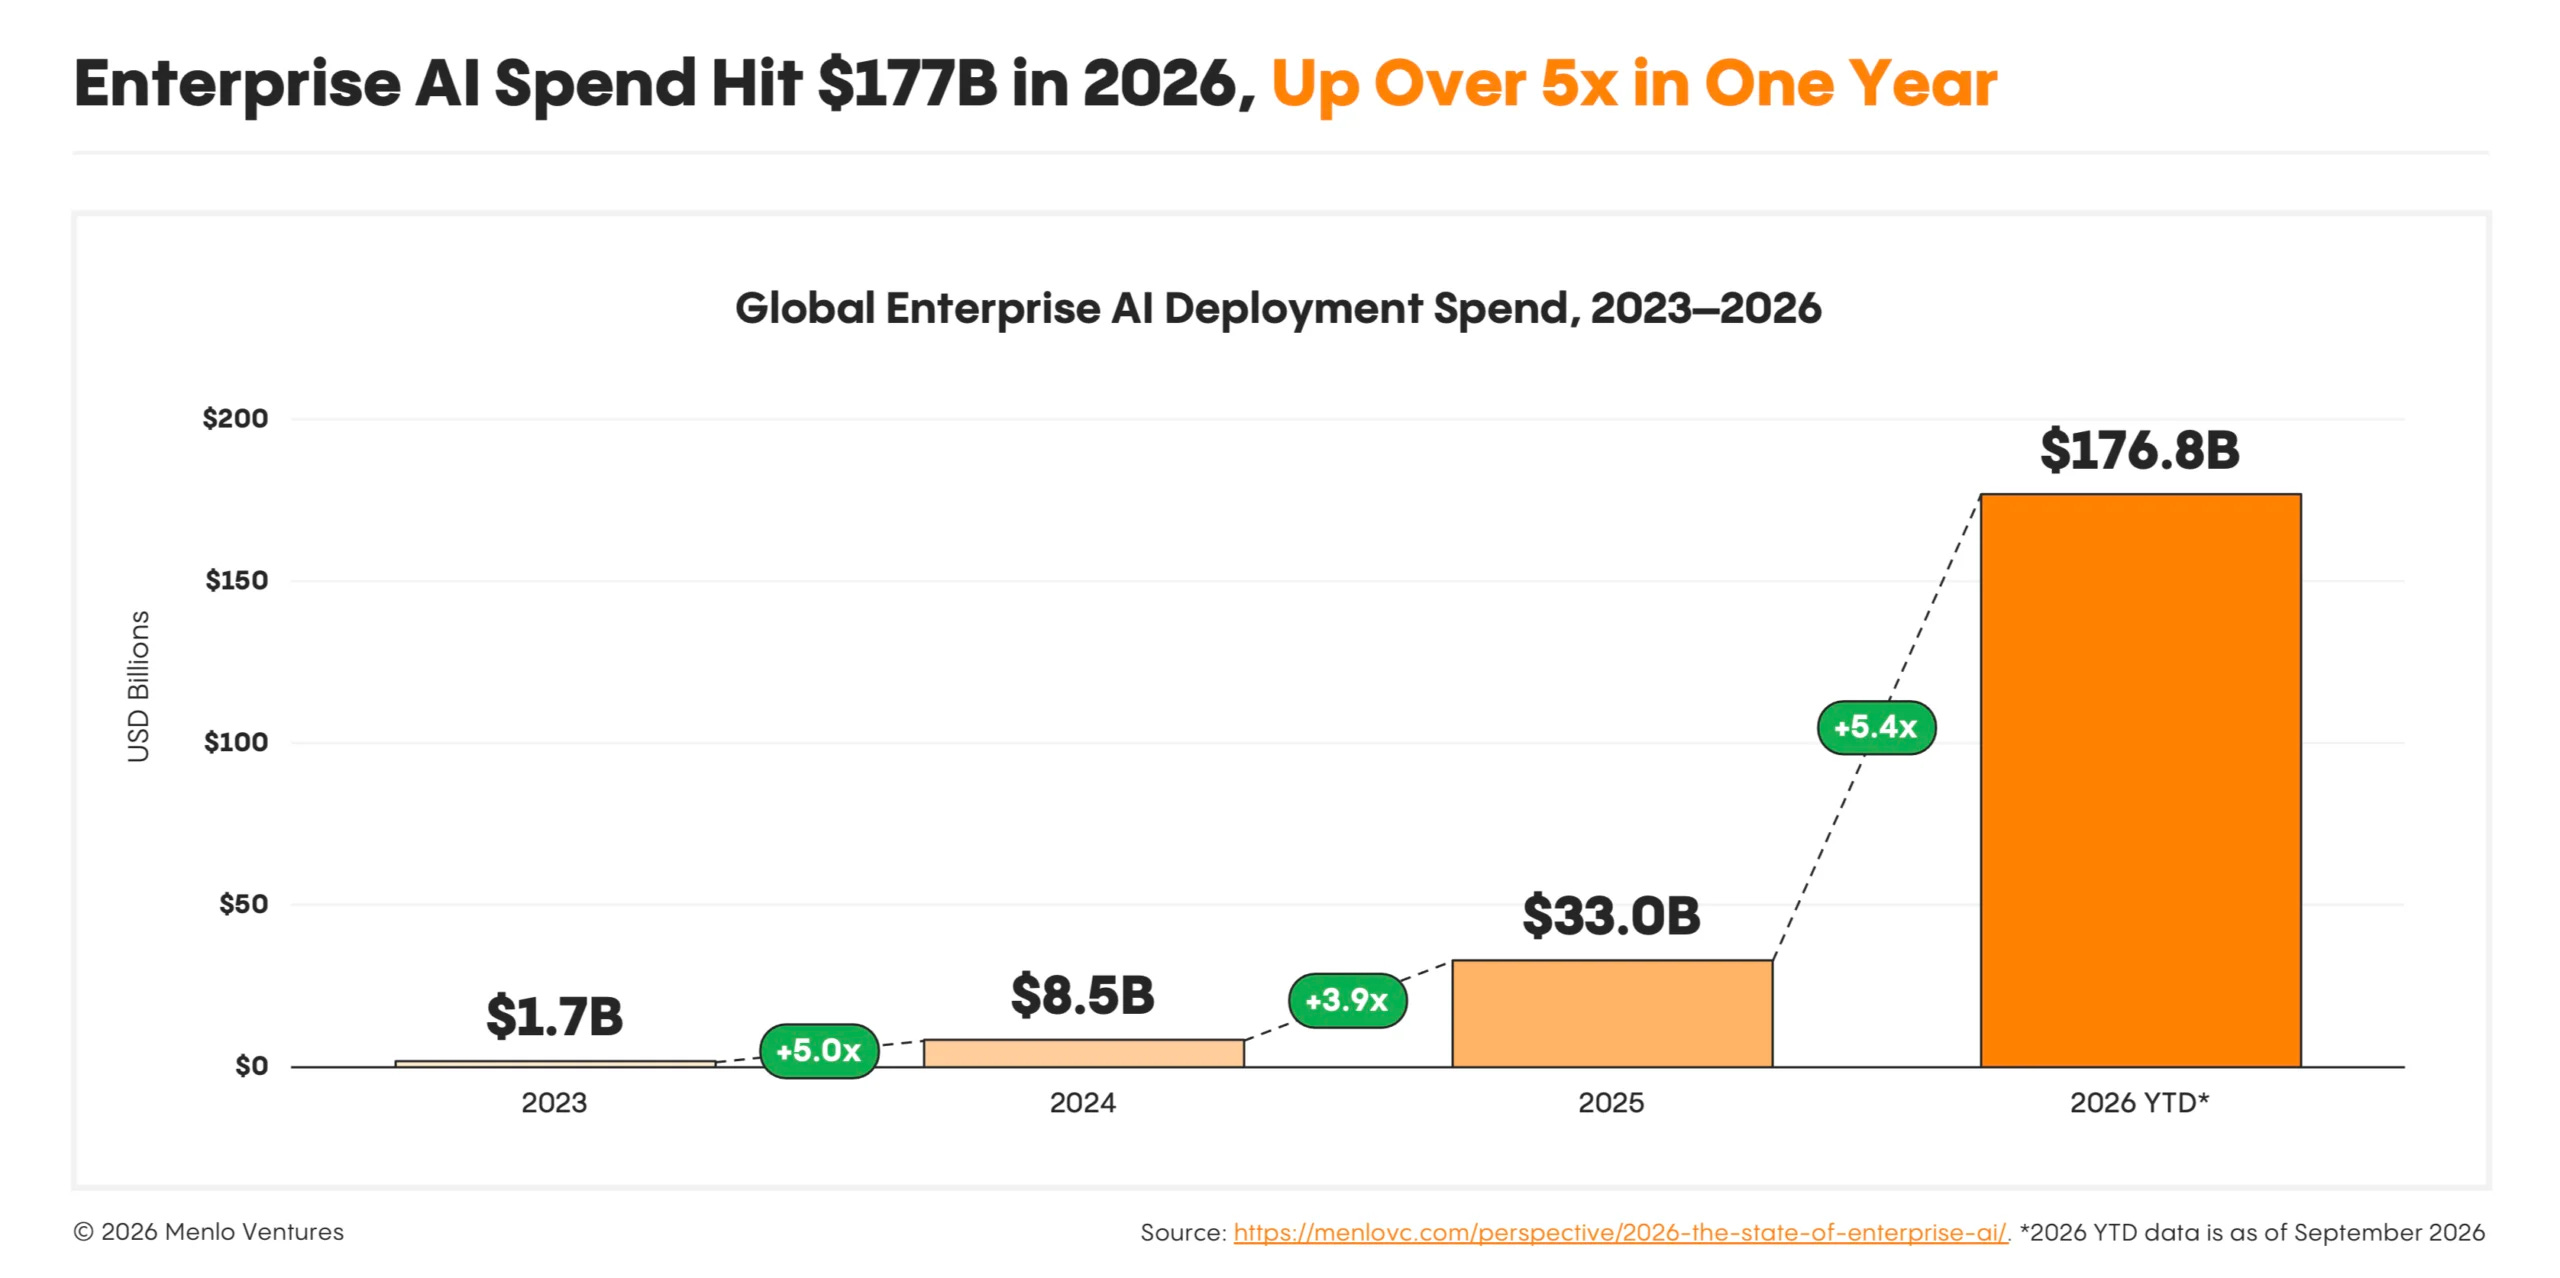
Enterprise generative AI deployment spending is a thing in process that has grown roughly 100x in three years. It went from $1.7B in 2023 to $8.5B in 2024 (5.0x) and $33B in 2025 (3.9x). By September 2026, spending reached $176.8B, up 5.4x from last year. Anthropic owns the top end of all of this due to its dominant AI coding models that are also proficient in Agentic AI.
Does the Recursive Self Improvement Angle make Sense?
This has very little to do with speculative recursive self-improvement (RSI) capabilities, or Claude being able to help train its next generation of frontier models (faster), and everything to do with the capital Anthropic has been able to raise where Alphabet and Amazon have significant equity stakes in the business, accompanied by Cloud partnerships and a diversified financial backing across Technology.
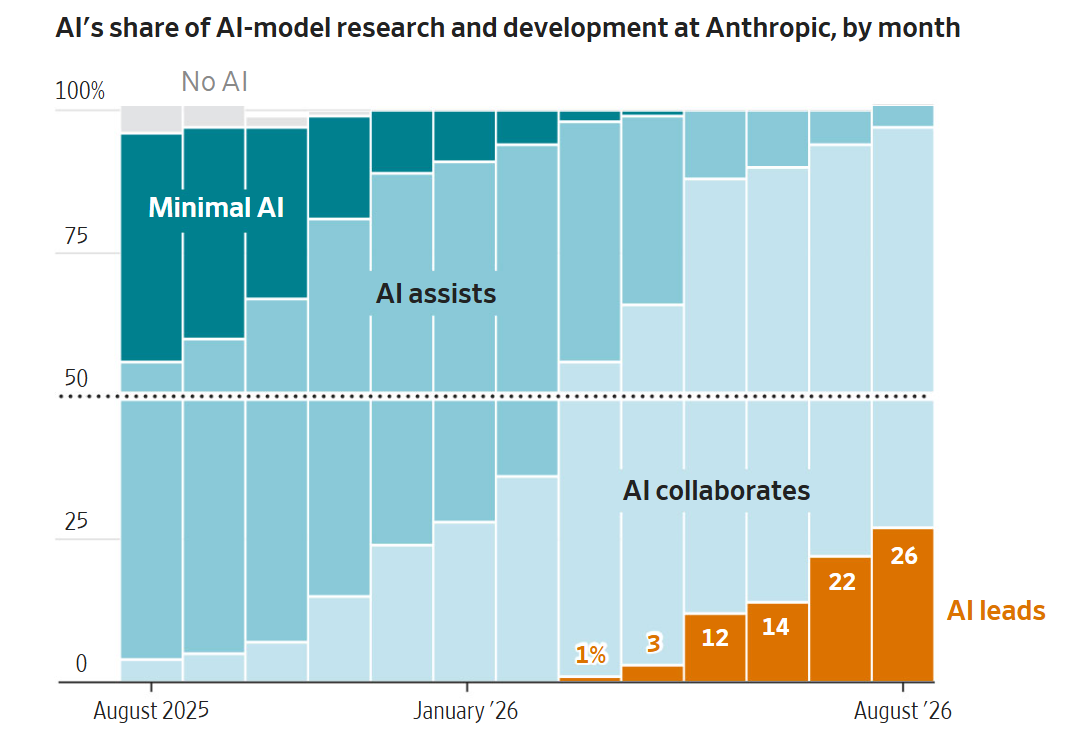

Anthropic’s RSI marketing stunt reeks of the desperation of an overvalued IPO. Of Billionaire co-founders pretending, they are ambassadors of the new world. As growth slows this will be an important marketing angle to monitor.
Spooky RSI in the Duopoly
America and their duopolies. BigAI is following a familiar patterns with Anthropic and OpenAI. American seems a capitalism of dualities, with industries typically having just two major winners.
Anthropic’s S-1 and the wishful oratory of its CEO keeps on a marketing hacks that is both a boast and a warning that the company is on the cusp of creating a model capable of recursive self-improvement (RSI). But true RSI would be general and across industries and totally autonomous, not some gimmick of Claude Code building the next Claude Opus model or accelerating the cadence a bit faster. In a world where AI is not leading much in the real economy, Anthropic’s exhibition of RSI needs some fact checking. Generative AI is conspicuously absent from being meaningful contributor to productivity in the real world.
Anthropic’s concentration of the top AI researchers and its ability to retain them has been pretty uncanny since 2023 which has contributed to a significant edge. Whereby its LLMs are significantly ahead of OpenAI and Google, it’s closest American rivals. If talent, access to capital and BigTech’s hyperscaler support isn’t a moat, I don’t know what is. In these days of watered down AGI and RSI definitions, that are mere shadows of their original definitions, RSI is the point at which AI grows so good at training itself that it spawns a dramatic acceleration of AI capabilities. Meanwhile agent swarms feel more like cybersecurity threats and layoff pressures in 2026, rather than significant new capabilities for most of us in society and in the labor market.
Anthropic's own language around RSI is itself disturbing, grandiose and feels fundamentally out of touch. Anthropic’s models are valuable mostly for their AI coding supremacy and Claude Code’s share of the top spectrum of Spend at the biggest American companies may only be temporary. There’s no guarantee Anthropic is the last answer to this equation.
Texas Turns Blue 🔵
The Midterms significantly extends Moratoriums and delays many datacenters stuck in limbo due to various bottlenecks. The “Blue Tsunami” could also results in Elon Musk, Starlink and other investigations and public hearings by Congress with increasing regulatory scrutiny. Billionaires were on the ballot and the Republic has spoken.

James Talarico’s victory in the US Senate race and Gina Hinojosa’s defeat of three-term Governor Greg Abbott in the State of Texas stole the headlines, symbolic because it has become the datacenter capital of AI where Billionaires have moved, which is the ultimate irony. Talarico made AI datacenters a central argument of his campaign.
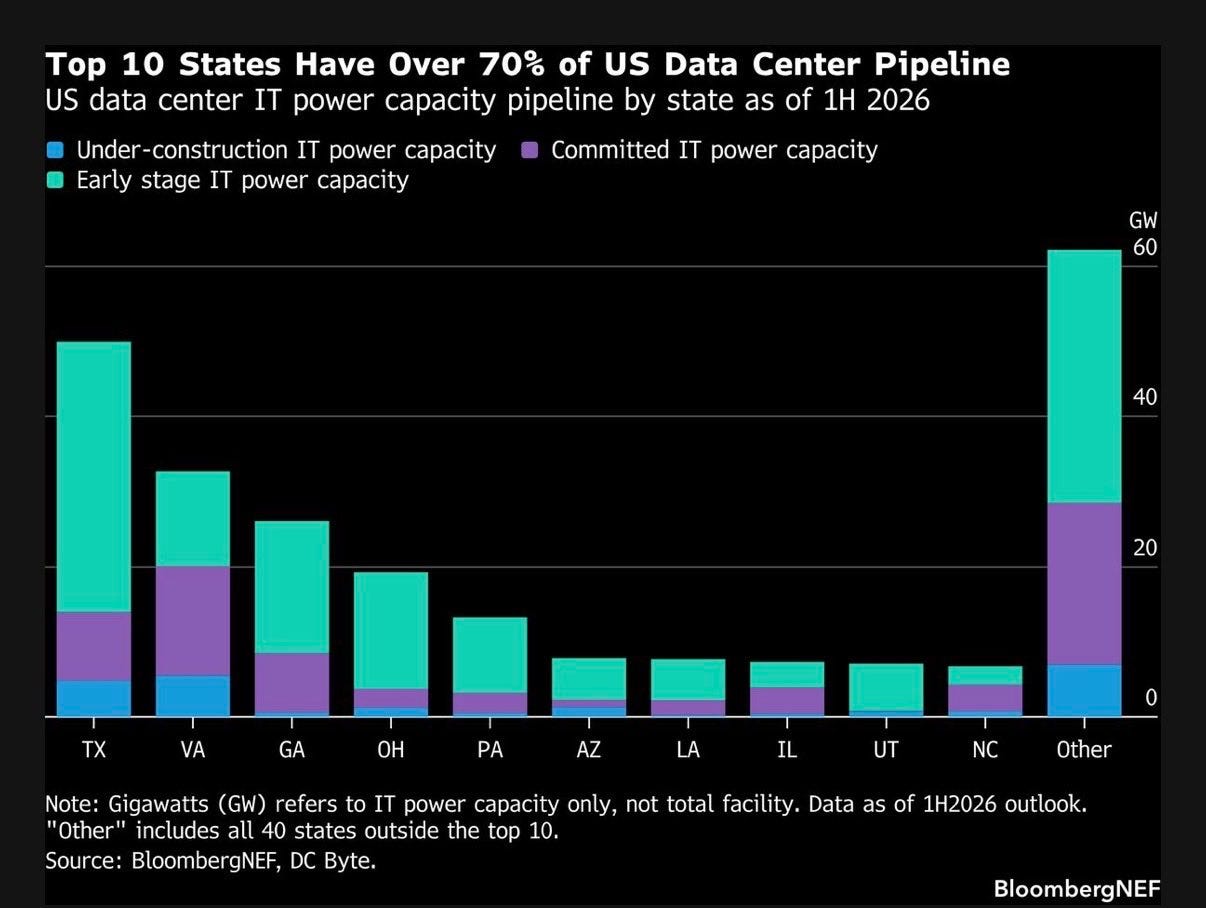
Roughly a quarter of the US data center capacity expected to come online by 2030 is in Texas, and Jefferies estimates that some 13.3 gigawatts of announced projects would be at risk under a Hinojosa moratorium.
Georgia and Ohio, two other large pipeline states, also elected Democratic governors who have promised a pause or a conditional freeze2.
The Pivotal Datacenter States all Turned Blue in the Blue Tsunami
Texas, Georgia, Ohio.